

Container spot freight rates on the transpacific and Asia-Europe continued on their completely divergent directions for the seventh straight week, with Asia-US east coast rates now hitting levels not seen since July 2022.
This week’s World Container Index (WCI) by Drewry saw its Shanghai-New York breach the $10,000 per 40ft level, the first time it has done so since during the latter days of Covid, after rising 7% this week to end at $10,394 per 40ft.
US freight forwarder Freight Right said the carriers’ pricing power from Asia into the US east coast remained stronger than to the west coast and some shippers desperate to secure space were booking at rates almost $1,000 higher than current index levels.
“East Coast pricing remains significantly higher, with rates now above $10,000 and reaching approximately $11,000 per container in some cases.
“Like the West Coast, the lane is experiencing constrained capacity and increasingly unstable vessel schedules,” it said.
The WCI’s Shanghai-Los Angeles leg increased 5% week-on-week to end at $7,712 per 40ft amid similar trade dynamics, and Freight Right warned that more concerning for shippers was the diminishing schedule reliability levels caused by a confluence of Asian port congestion and increasing numbers of blank sailings, leading to higher cases of rollovers at loading ports.
“The bigger operational concern is no longer price,” Freight Right added.
“Vessel schedules have become increasingly unreliable. A shipment can secure space and still see its scheduled departure pushed back several days.
“When a booking rollover is combined with a delayed vessel departure, total delays can approach two weeks,” it said.
And with nine transpacific blank sailings announced for next week compared to eight this week, according to Drewry’s Container Capacity Insight, the tight capacity outlook is set to continue and Drewry said it “expects rates to rise slightly next week amid impending pre-Golden Week demand and continued capacity management by carriers”.
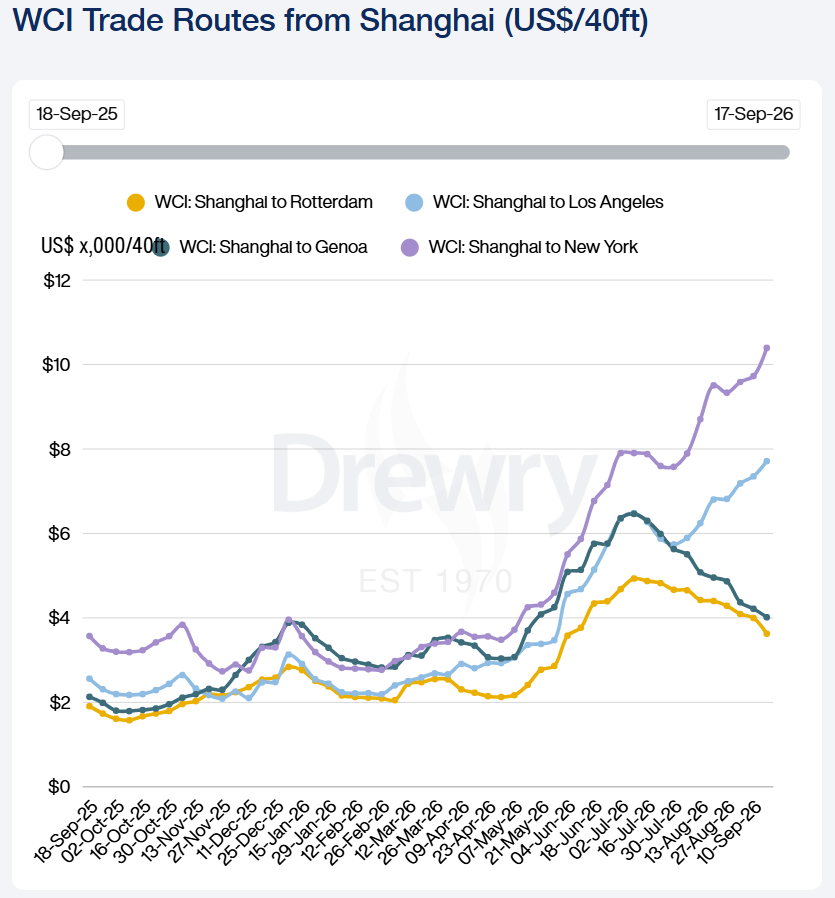
Source: Drewry
Meanwhile, the recent declines seen on the Asia–Europe trades accelerated this week, with its Shanghai-Rotterdam route down 9% on the previous week to $3,626 per 40ft, while the Shanghai-Genoa leg declined 5% to $4,016 per 40ft.
Comparing to the same period in 2022 – when Asia-US east coast were last at the same level as today – Asia-North Europe stood at around $9,000 per 40ft and Asia0-Mediterranean was at $11,000 per 40ft.
Despite the pricing weakness in comparison to the transpacific, analysts at Linerlytica noted that today’s Asia-Europe spot rates are still around double this time last year, and described current pricing as resilient, despite the drops.
“The freight rate resilience has been supported by stronger than expected demand even after the cargo demand peaked in May, and the severe port congestion in China in the last two months.
“Although congestion in Chinese ports is starting to clear from the peaks in early September, the congestion has shifted to Southeast Asia ports.
“Waiting times in Singapore have risen to over four days due to vessel bunching,” Linerlytica said earlier this week.
Meanwhile, Drewry’s Container Capacity Insight records four Asia-Europe blank sailings scheduled for next week, up from one this week, “indicating tighter capacity”.
“With tight capacity and continued congestion in Asia, Drewry expects Asia-Europe rates to decline slightly next week, as demand remains weak,” it said.
A further factor is the increasing number of carriers returning to Red Sea routings, which has the effect of injecting capacity simply through the shorter sailing distances.